English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
Global Supply Chain Scale-Up and Peptide Synthesis Manufacturing Innovations Meeting High Demand
Wellness |
2026-10-13 15:08:38
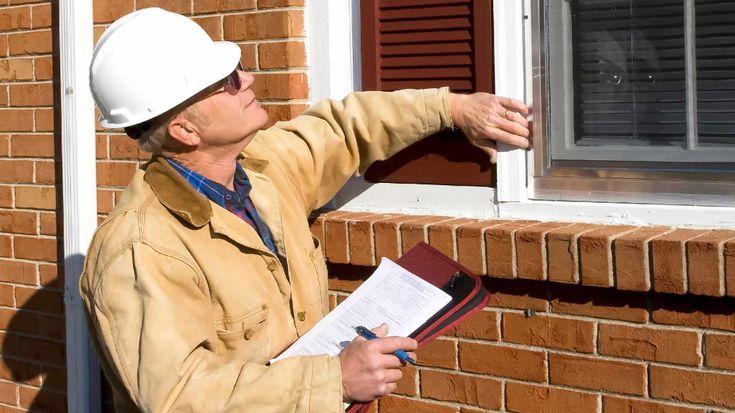
Home inspections can help property owners understand the condition of important household systems. A four point inspection focuses on four major areas: the roof, electrical system, plumbing, and heating and cooling equipment. Insurance companies may request this assessment when reviewing an existing home, particularly an older property, to better understand potential risks before deciding on coverage.
Homeowners researching Residential Four Point Inspection in Apopka FL may need an inspection when purchasing insurance, renewing a policy, or responding to an insurer's request for updated property information. The inspection provides a snapshot of the home's visible condition at the time of the visit. Requirements can differ among insurance companies, so homeowners should confirm the requested form, inspection standards, and submission deadlines with their insurer.
The roof is one of the four main areas reviewed during a typical inspection. An inspector may examine the visible roofing materials, estimate the roof's age when information is available, and look for signs of deterioration or damage. Missing shingles, damaged flashing, visible leaks, and water stains may require further attention. The roof's condition can influence an insurer's assessment because roofing problems may increase the risk of water intrusion and related damage.
Electrical systems are another important part of the assessment because faulty wiring and outdated components can create safety concerns. Depending on accessibility, the inspector may review the electrical panel, visible wiring, breakers, and other accessible components. Signs of overheating, damaged wiring, or improperly installed equipment may be noted for further evaluation. Homeowners should not remove electrical panel covers or attempt repairs themselves unless qualified to do so.
Plumbing problems can lead to leaks, water damage, and costly repairs if left unresolved. During the inspection, the inspector may review visible supply lines, drain connections, fixtures, and signs of leakage or corrosion. Water stains beneath sinks, damp cabinets, and visible pipe deterioration can indicate concerns that deserve attention. Since many plumbing components are hidden behind walls or beneath floors, a four point inspection is not a comprehensive examination of every pipe in the property.
Heating and cooling systems help maintain indoor comfort, but their condition also matters when an insurer evaluates a property. An inspector may identify the type of equipment, estimate its age when possible, and examine accessible components for visible damage or concerns. Maintenance records and service documentation can help clarify the system's history. If the equipment appears damaged or does not operate normally, a qualified HVAC technician may need to investigate further.
A Four Point Inspection is easier to complete when the inspector can access the relevant areas safely. Before the appointment, clear access to the electrical panel, water heater, plumbing fixtures, heating and cooling equipment, and attic entry if needed. Gather available information about the roof and major systems, including installation dates, repair invoices, and maintenance records. Do not make temporary changes simply to conceal an existing problem.
The report generally records observations about the four primary systems and may include photographs, equipment details, and notes about visible deficiencies. The format and required information depend on the insurer and the applicable inspection form. Homeowners should review the completed report for accuracy and ask the inspector to explain any unclear findings. If a significant concern is identified, additional testing or evaluation may be recommended.
An inspection does not automatically mean that an insurer will approve or deny coverage. The insurance company makes that decision based on its underwriting rules, the report, and other relevant information. If deficiencies are documented, the insurer may request repairs, supporting documentation, or a follow-up assessment. Homeowners should ask which issues need attention first and retain invoices, permits, and photographs when repairs are completed.
When selecting an inspector, ask about relevant experience, professional credentials, insurance, report turnaround time, and familiarity with the requirements of your insurance company. Confirm the inspector can complete the specific four point form requested by the insurer. It is also helpful to understand what the inspection excludes, how inaccessible areas are handled, and whether the quoted fee includes photographs and report delivery.
Routine maintenance can help homeowners address concerns before they become more serious. Arrange roof evaluations when needed, use qualified professionals for electrical repairs, repair plumbing leaks promptly, and follow manufacturer recommendations for HVAC servicing. Keep records of completed work and equipment replacements. Although maintenance cannot guarantee insurance approval, accurate documentation helps demonstrate how the property's major systems have been cared for over time.
A four point inspection helps document the visible condition of important home systems for insurance review. Understanding the process, preparing access to key areas, and gathering maintenance records can make the appointment more efficient. For homeowners in Apopka, Florida, confirming insurer requirements in advance and addressing known concerns with qualified professionals can help reduce avoidable delays and support informed decisions about property maintenance and insurance coverage.