English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
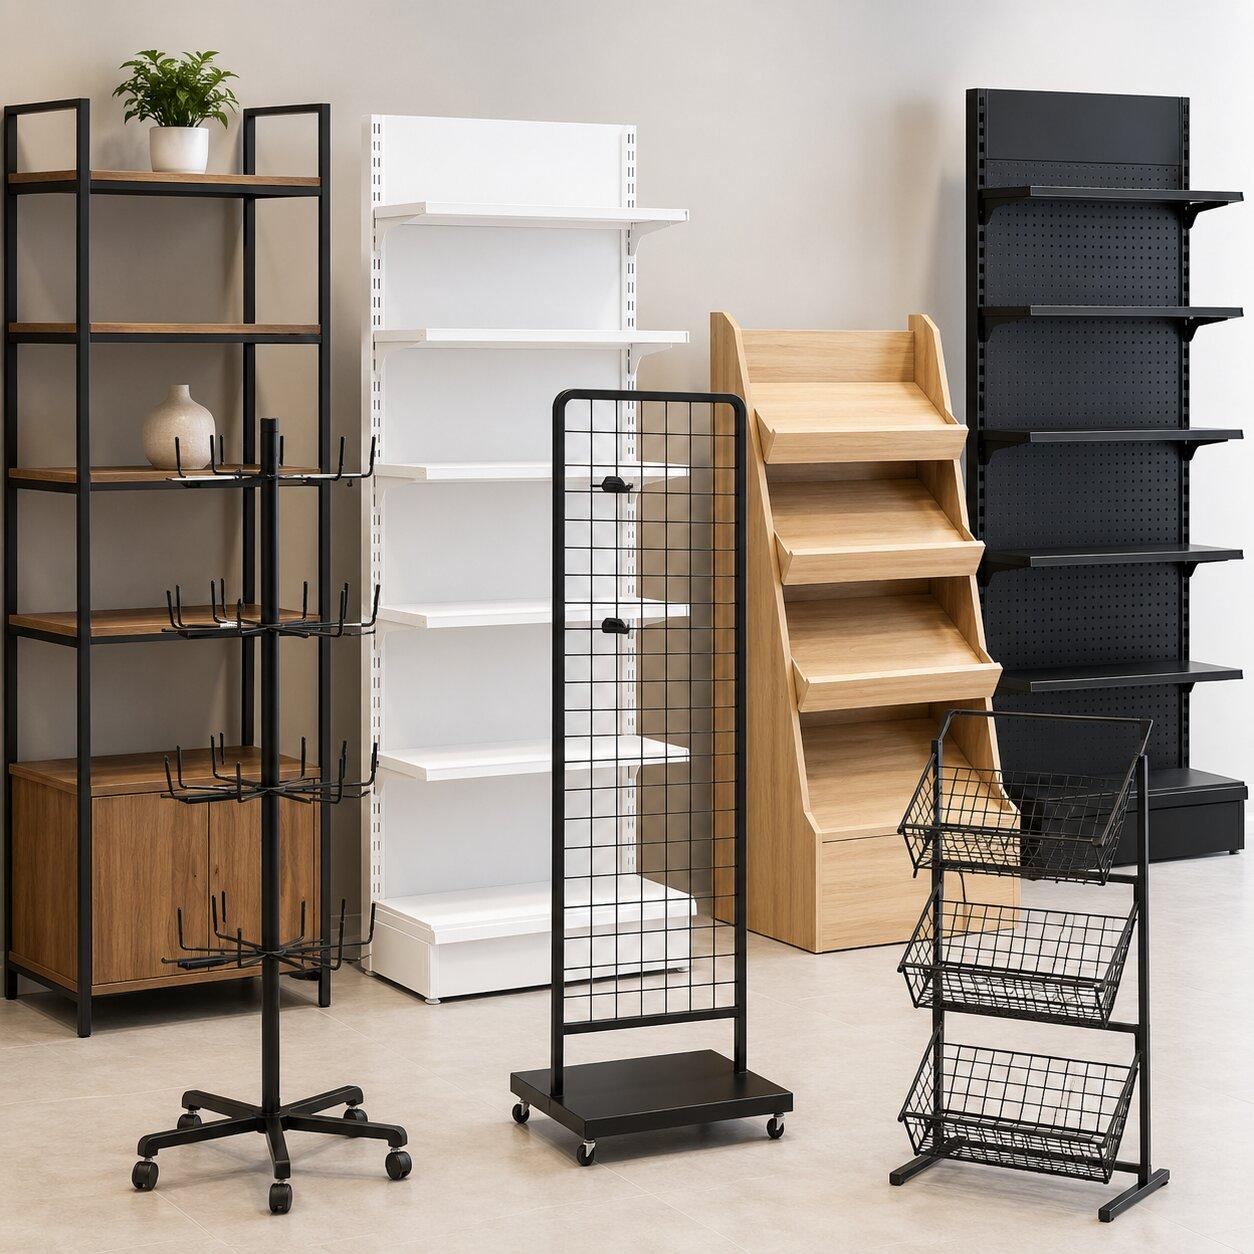
Looking to Get the Right Cigarette Racks in the UK for Your Retail Shop?
Shopping |
2026-10-23 11:00:01
A rigorous Core Banking Solution Market Analysis reveals how architectural agility, regulatory compliance governance, and total cost of ownership calculations govern vendor selection across global financial institutions. Segmenting the sector by deployment model demonstrates that cloud-based core banking solutions hold the largest revenue and adoption share, favored by challenger banks, mid-tier regional lenders, and retail banking subsidiaries seeking rapid time-to-market and elastic infrastructure scaling. Meanwhile, on-premises deployments exhibit strong expansion among large tier-one commercial banks and regulated national institutions that require direct physical control over core hardware to satisfy strict sovereign data-residency statutes. Hybrid architectures are simultaneously gaining popularity among universal banks modernizing customer channels incrementally while preserving core mainframe stability.
Analyzing the market by core functionality and end-user institution highlights distinct investment priorities across retail, corporate, and wealth banking. Transaction processing and account management represent the high-volume operational core, handling real-time deposits, multi-currency payments, standing instructions, and interest accrual engines across millions of customer accounts. Risk management and compliance management modules represent high-growth strategic priorities as banks integrate automated credit scoring, liquidity stress-testing, anti-money laundering screening, and real-time regulatory reporting directly into core workflows. Across bank sizes, large tier-one banks generate substantial multi-year transformation contract values, while community banks, credit unions, and microfinance institutions drive high-volume demand for turnkey cloud SaaS core subscriptions.
Competitive dynamics within the global core banking landscape feature intense rivalry between established enterprise banking software incumbents and next-generation cloud-native disruptors. Established global leaders—including FIS, Finastra, Temenos, Oracle, Infosys Finacle, TCS BaNCS, and NCR Voyix—leverage deep functional breadth, proven multi-country regulatory localization packs, and vast system-integrator ecosystems. Simultaneously, cloud-native challengers such as Mambu, Thought Machine, 10x Banking, and nCino compete aggressively on microservices composability, zero-downtime continuous deployment, and rapid greenfield launch timelines.
Despite compelling strategic imperatives, complex operational and technical challenges require careful management during core transformations. Legacy core migration carries significant execution risk; decades of undocumented custom code, tangled point-to-point integrations, and intricate data cleansing requirements can trigger cost overruns and schedule delays if poorly governed. Additionally, acute shortages of experienced core banking architects, strict third-party cloud vendor concentration oversight by financial regulators, and cybersecurity risks during parallel data synchronization remain key hurdles that institutions must navigate through phased, low-risk migration strategies.
Top Trending Reports :
Pro Self Hosted Digital Payment Gateway Market
Real Estate Investment Trust Market
Real Estate Management Solution Market
Revenue Based Financing Market